Acreage & Rural Property Financing
Getting you the mortgage you deserve
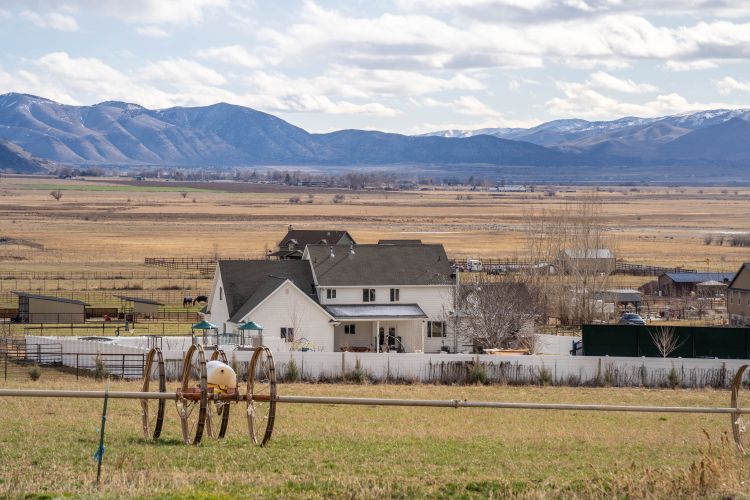
Financing an Acreage Isn't the Same as Financing a House in the City
Dreaming of more space, privacy, a workshop, room for horses, or a country property outside the city?
Acreage living can be incredible—but financing an acreage or rural property can come with additional considerations that don't typically apply to a standard residential property.
At Value Mortgage Solutions, I understand that rural properties don't always fit neatly into a traditional lending box.
Whether you're purchasing an acreage near Okotoks, High River, Foothills County, Calgary or elsewhere in Alberta, I'll help you understand your financing options before you make an offer.
Why Is Acreage Financing Different?
When a lender finances a property, they're not only approving the borrower—they're also approving the property being used as security for the mortgage.
With an acreage, lenders may look more closely at factors such as:
- Property size and number of acres
- Location and proximity to populated areas
- Residential versus agricultural use
- Zoning and land-use designation
- Condition and marketability of the property
- Well and septic systems
- Outbuildings, barns, shops and other structures
- Access to the property
- Whether the property produces income
- Appraised value attributable to the home versus additional land or improvements
This means two properties with the same purchase price can have very different financing options.
How Many Acres Can I Finance?
There isn't one universal acreage limit that applies to every lender.
Some lenders are comfortable with larger parcels, while others may restrict how much land they will consider as part of the residential mortgage.
The lender may also consider whether the additional acreage is typical for the area and whether the property's primary use is residential rather than farming or commercial activity.
This is why it's important to review the actual property—not just the purchase price.
What About a House With a Shop, Barn or Outbuildings?
Found the perfect acreage with a huge heated shop?
That's great—but make sure we review it before assuming the lender will assign the same value to the shop that you do.
Detached garages • Workshops • Barns • Riding arenas • Quonsets • Guest houses • Storage buildings • Agricultural buildings
Depending on the lender and appraisal, some structures may contribute to the property's value differently than the primary residence.
My job is to understand the property upfront and match it with a lender whose guidelines make sense for that particular acreage.
Well & Septic Systems
Many rural Alberta properties don't have municipal water and sewer services.
Instead, they may rely on a:
Private well • Cistern • Septic tank • Septic field • Other private water or wastewater system
Depending on the property and lender, additional information or inspections may be required.
Understanding these requirements early can help prevent surprises after you've already written an offer.
Residential Acreage vs. Farm Financing
This distinction is extremely important.
A property can look like an acreage but have characteristics that cause a lender to view it differently.
Lenders may ask whether the property includes:
- Active farming operations
- Significant agricultural land
- Farm income
- Livestock operations
- Commercial buildings
- Agricultural leases
- Large parcels of productive farmland
If the property is primarily being purchased as your personal residence, residential acreage financing may be available.
If the property is primarily agricultural, commercial or income-producing, a different financing approach may be required.
Buying an Acreage? Get Pre-Approved Before You Write the Offer.
A traditional mortgage pre-approval generally focuses on you as the borrower.
It doesn't automatically mean every acreage you find will qualify for financing.
That's why I recommend sending me the property listing before you write an unconditional offer.
We can review the property details and identify potential financing concerns early.
Already Own an Acreage?
Acreage financing isn't limited to purchases. Depending on your situation, you may also have options for:
Mortgage Renewals
Review your mortgage before automatically signing your lender's renewal offer.
Refinancing
Access available equity for renovations, investments, major purchases or other financial needs.
Debt Consolidation
Use available home equity to potentially consolidate higher-interest debts into a mortgage solution.
Home Improvements
Looking to renovate the house, build or improve a shop, upgrade your property or complete other major improvements? We can review potential financing strategies.
What If the Bank Says No?
A decline from your bank doesn't necessarily mean the property can't be financed.
Sometimes the challenge isn't the borrower.
It's the property.
One lender may have concerns about acreage, location, property size, zoning or outbuildings while another lender may have guidelines that better fit the property.
As a mortgage broker, I can review options across different types of lenders, including:
Prime Lending • Alternative Lending • Private Lending • Equity-Based Solutions
The objective is to find a financing structure that fits both the borrower and the property.
Local Knowledge Matters With Rural Financing
A property 10 minutes outside Okotoks can be very different from an acreage located significantly farther from a major population centre.
Location, marketability, property type and surrounding comparable sales can all affect the lender's decision.
That's why working with someone familiar with acreage and rural financing in Alberta can make a significant difference.
Looking for an Acreage in Alberta?
Before you fall in love with the property, let's make sure we understand the financing.
Send me the listing and I'll help you determine what questions we need answered and what financing options may be available.
THINK OUTSIDE OF THE BOX.
Ken Faminoff
Senior Mortgage Broker
Value Mortgage Solutions | Mortgage Architects – Team Borle
Serving Okotoks, Calgary, High River, Foothills County, Southern Alberta and clients throughout Alberta
